Quick Answer
The five main kitchen remodeling financing options in Las Vegas are HELOCs, fixed-rate home equity loans, cash-out refinancing, personal loans, and contractor or retailer financing, each suited to different project sizes, credit profiles, and payment-certainty needs. The right choice depends on how much equity you have, whether your contractor’s price is fixed or still being scoped, and whether you value a stable monthly payment over fast access to funds.
Nearly every stalled kitchen remodel in the Las Vegas valley traces back to the same root cause: homeowners picked a financing product before they understood its trade-offs. With kitchen remodeling financing options Las Vegas homeowners can choose from ranging widely in structure, rate, and risk, the wrong match can turn a straightforward cabinet-and-countertop upgrade into a stressful, over-budget ordeal. This guide breaks down five real financing paths, what they cost, who they fit, and the questions that separate a smart borrowing decision from an expensive mistake.
Industry data backs up why financing matters more than ever. A recent homeowner remodeling interest index found that rising project costs and borrowing uncertainty caused many homeowners to delay remodels in late 2026, even when they wanted to move forward. Understanding your financing options before you call a contractor removes that hesitation and lets you plan with confidence.
What Does a Kitchen Remodel Actually Cost in Las Vegas?
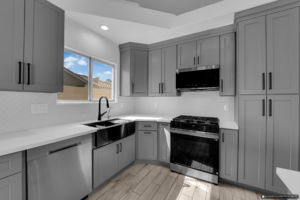
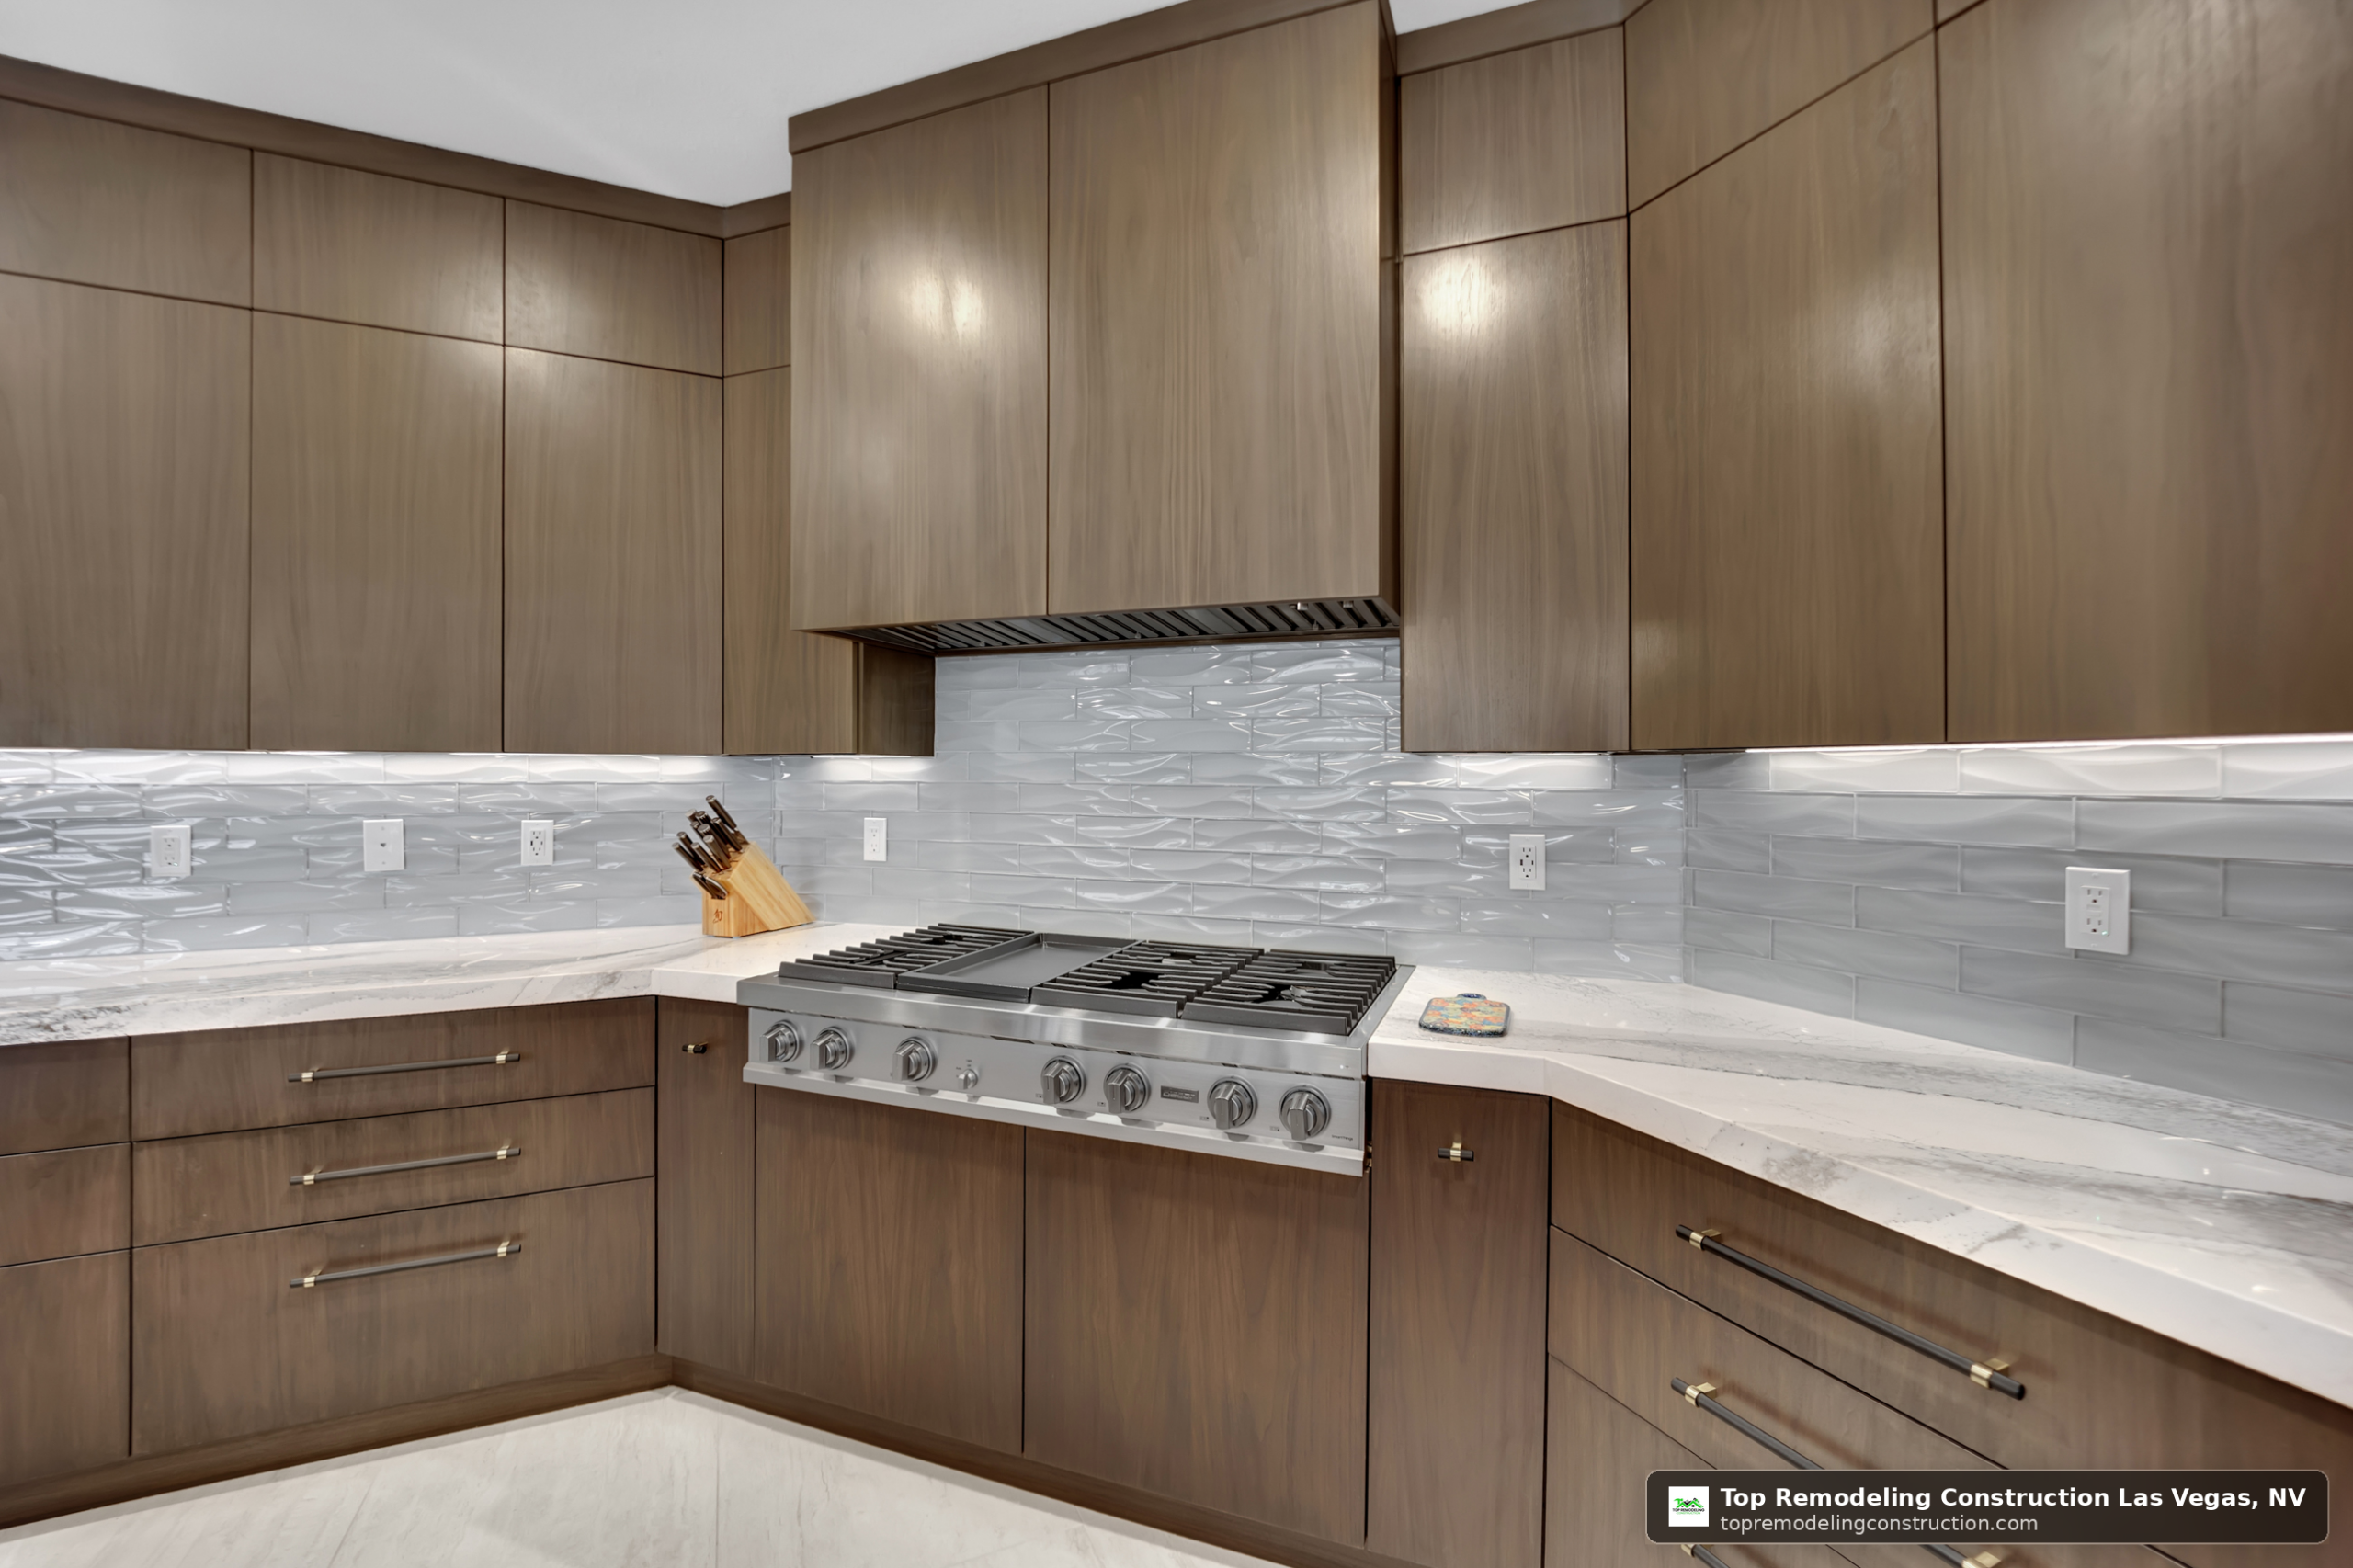
Pricing varies based on your specific project, but national and regional benchmarks give useful planning ranges. A cosmetic refresh (paint, hardware, lighting, backsplash) typically runs $10,000 to $20,000. A substantial full update with new cabinets, countertops, and appliances generally falls between $15,000 and $50,000, while an upscale remodel involving layout changes, structural work, or premium materials can exceed $50,000.
| Project Scope | Typical Planning Range | Common Work |
|---|---|---|
| Cosmetic refresh | $10,000–$20,000 | Paint, hardware, lighting, backsplash, refinishing |
| Midrange renovation | $15,000–$50,000 | New cabinets, countertops, flooring, appliances |
| Upscale or structural remodel | $50,000+ | Layout changes, wall removal, custom millwork |
A smart planning rule is to reserve 10% to 20% for contingency on top of your contracted price, since unexpected plumbing, electrical, or structural discoveries are common in older Las Vegas homes. On a $40,000 project, that means budgeting an extra $4,000 to $8,000, which pushes your realistic financing target closer to $48,000 if your scope isn’t fully locked in yet. For a detailed look at how timing and scope affect your schedule, see our kitchen remodeling timeline guide.
What Are the Main Kitchen Remodeling Financing Options?
Most Las Vegas homeowners choose from five financing paths: a home equity line of credit (HELOC), a fixed-rate home equity loan, cash-out refinancing, an unsecured personal loan, or financing offered directly through a contractor or retailer. Each option trades off interest rate, payment predictability, speed of funding, and risk to your home differently.
The right fit depends on project size, your credit profile, how much equity you’ve built, your tax situation, and whether certainty matters more to you than flexibility. Homeowners planning government-backed renovation financing should also review HUD’s Nevada housing resources and the FHA 203(k) Rehabilitation Mortgage Insurance Program, which bundles renovation costs into a single mortgage for qualifying buyers and owners.
HELOC vs. Fixed-Rate Home Equity Loan: Which Fits Your Project?
A HELOC is a revolving line secured by your home, and interest typically applies only to funds actually drawn, not the full approved limit. This makes it a strong fit for phased kitchen projects where costs arrive in stages: demolition, cabinets, countertops, then final installation. A 2026 market benchmark placed the average rate for a $30,000 HELOC at 7.36% for a borrower with a 700 FICO score and 80% combined loan-to-value ratio, though other 2026 estimates put typical rates closer to 8.5% to 9.5% depending on lender and market conditions, according to current home improvement loan rate data.
A fixed-rate home equity loan, by contrast, delivers a lump sum with a locked interest rate and predictable monthly payments, generally around 7.75% to 8.5% in 2026 estimates. This structure fits better once your contractor has issued a firm, all-in price and you want zero payment surprises over the loan term.
Best for: Phased projects
2026 avg rate: ~7.36%–9.5%
Risk: Payments can rise
Best for: Firm-price contracts
2026 est. rate: ~7.75%–8.5%
Risk: Less flexible if scope grows
Best for: Smaller, fast-funded jobs
Risk: Higher rate, no equity needed
On a $30,000 HELOC balance at 7.36% amortized over 10 years, the principal-and-interest payment lands near $351 a month. That’s a useful benchmark, but your actual terms will depend on your lender, credit score, and how much equity your home carries. For homeowners budgeting a full kitchen overhaul, our kitchen remodeling Las Vegas guide walks through how scope decisions affect overall project cost.
What About Cash-Out Refinancing, Personal Loans, and Contractor Financing?
Cash-out refinancing replaces your existing mortgage with a larger one and gives you the difference in cash. It can make sense when current mortgage rates are near or below your existing rate, but refinancing resets your loan term and comes with closing costs, so it’s rarely the best tool for smaller remodels.
Personal loans are unsecured, funded quickly, and don’t require home equity, making them a reasonable option for cosmetic refreshes in the $10,000 to $20,000 range. The trade-off is a higher interest rate than secured products, since the lender takes on more risk. CNBC’s comparison of home improvement loans is a useful starting point for shopping rates across lenders before committing.
Contractor or retailer financing is convenient because it’s arranged at the point of sale, but terms vary enormously. Some offer legitimate promotional periods with 0% interest; others carry deferred-interest structures that charge back-dated interest if the balance isn’t paid in full by a deadline. Always read the term sheet closely, and compare it against what an independent lender would offer.
Market-wide, remodeling activity is expected to keep growing: the National Association of Home Builders projects continued remodeling growth into 2026 and beyond, according to NAHB’s 2026 remodeling outlook, and the kitchen and bath industry anticipates a new market era as demand patterns shift, per industry projections for 2027. That growth means more financing products are entering the market, so comparing offers carefully pays off.
What Questions Should You Ask a Lender Before Signing?
Before committing to any financing product, ask these questions directly:
- Is the rate fixed or variable? Variable rates can rise mid-project, changing your monthly payment.
- Are there draw fees, annual fees, or prepayment penalties? These add real cost beyond the headline rate.
- What’s the full APR, including closing costs? A low advertised rate can hide high fees.
- How long is the draw period, and what happens after it ends? HELOCs often convert to repayment mode with a different payment structure.
- Does my contractor require deposits before draws are available? Timing mismatches can delay your project.
It’s also worth asking your contractor how they structure payment milestones, since that affects which financing product makes sense. Our team at expert kitchen remodeling services in Las Vegas walks clients through milestone-based billing so financing draws align with actual work completed.
What Red Flags Signal a Bad Financing Deal?
Watch for these warning signs when evaluating any financing offer:
- Pressure to sign same-day financing without time to compare rates. Legitimate lenders don’t need a same-visit decision.
- Deferred-interest promotions with unclear payoff deadlines. Missing the deadline by even one day can trigger retroactive interest on the full balance.
- No written explanation of what happens if your project scope grows. This matters most with fixed lump-sum loans.
- Contractors who require large upfront payments before permits are pulled. Review the City of Las Vegas online permits list and confirm permitting is handled properly, since permit requirements are detailed in the city’s official permit issuance requirements.
- Lenders unwilling to disclose the full APR in writing. This is a basic transparency standard.
Choosing a licensed, reputable contractor also reduces financing risk, since guidance on vetting Las Vegas general contractors notes that properly licensed contractors are far less likely to generate the change orders and scope creep that blow past financed budgets. If you’re also weighing outdoor upgrades alongside your kitchen, our pool remodeling Las Vegas page covers financing-adjacent planning for larger whole-home projects.
Key Takeaways
- Las Vegas kitchen remodels typically range from $10,000 for cosmetic refreshes to $50,000+ for upscale, structural projects, and pricing varies based on your specific project scope and material selections.
- HELOCs suit phased projects with evolving costs, while fixed-rate home equity loans fit firm, all-in contractor quotes better.
- 2026 HELOC rates ranged roughly 7.36% to 9.5%, and fixed home equity loan rates ran approximately 7.75% to 8.5%, though your actual rate depends on credit and equity.
- Always budget a 10% to 20% contingency on top of your contracted price before finalizing a loan amount.
- Deferred-interest contractor financing can be valuable but carries real risk if the balance isn’t paid off by the promotional deadline.
- Confirm permitting is handled correctly before releasing large payments, since proper permits protect both your investment and your home’s resale value.
- Comparing at least two to three lenders before signing is the single best way to avoid overpaying on financed remodels.
People Also Ask
What credit score do I need to finance a kitchen remodel in Las Vegas?
Most home equity products require a credit score around 680 or higher for the best rates, though some personal loan and contractor financing options accept lower scores at a higher interest rate. A 700+ score typically unlocks the most competitive HELOC and home equity loan terms.
Is it better to use a HELOC or a personal loan for a kitchen remodel?
A HELOC generally offers a lower rate because it’s secured by your home, making it better for larger projects over $20,000. A personal loan is faster to obtain and doesn’t put your home at risk, which makes it a reasonable fit for smaller cosmetic updates.
How much equity do I need for a home equity loan in Las Vegas?
Most lenders require you to retain at least 15% to 20% equity after the loan, meaning your combined loan-to-value ratio typically can’t exceed 80% to 85%. An appraisal will confirm your home’s current value and available equity.
Does financing a kitchen remodel increase my home’s resale value?
Kitchen remodels consistently rank among the higher-return renovation projects, though actual return depends heavily on quality of workmanship and how the finishes match neighborhood expectations. Financing itself doesn’t add value, but completing a well-executed remodel generally does.
Frequently Asked Questions
What’s the fastest way to get kitchen remodel financing approved?+
Personal loans and contractor financing typically fund fastest, often within one to five business days, since they don’t require a home appraisal. Home equity products take longer, usually two to six weeks, because they require an appraisal and title work.
Can I finance a kitchen remodel with no equity in my home?+
Yes, an unsecured personal loan or qualifying contractor financing plan doesn’t require home equity, though rates will typically be higher than secured options. FHA 203(k) loans can also help buyers finance renovations into a purchase mortgage in certain situations.
Should I get the contractor’s final quote before applying for financing?+
Yes, locking in a detailed, itemized quote first helps you borrow the right amount and choose the right loan structure. Applying for financing before you have a firm scope often leads to borrowing too little or paying interest on unused funds.
What happens if my kitchen remodel costs more than I financed?+
If you used a HELOC, you may be able to draw additional funds up to your credit limit. If you used a fixed lump-sum loan, you’ll likely need a second financing source, which is why budgeting a 10% to 20% contingency upfront matters so much.
Are kitchen remodel loan interest payments tax deductible?+
Interest on home equity loans and HELOCs may be tax deductible if the funds are used to substantially improve the home that secures the loan, but rules vary by individual tax situation. Consult a tax professional to confirm how current rules apply to your specific circumstances.
How do I choose between a kitchen remodel and a bathroom remodel first if my budget is limited?+
Prioritize based on which space has more functional or safety issues and which offers better return relative to your home’s value. Many homeowners phase projects, starting with a full home remodeling plan that sequences kitchen and bathroom work around a single financing strategy.
Choosing the right financing path is just as important as choosing the right contractor. If you’re ready to turn your kitchen remodel plans into a firm, itemized quote so you can shop financing with confidence, reach out to the team at Top Remodeling Construction’s kitchen remodeling contractors in Las Vegas. We’ll help you scope the project accurately, understand your kitchen remodeling options in Las Vegas, and connect the dots between your budget and the financing product that fits it. Visit Top Remodeling Construction or contact us today for a custom quote tailored to your home and goals.